Table of Contents (11 Sections)↓
1. Statutory Legal Framework & Inland Revenue Act No. 24 of 2017
Withholding Tax in Sri Lanka operates primarily under Chapter VIII (Sections 83 to 90) of the Inland Revenue Act No. 24 of 2017, as amended by Subsequent Amendment Acts No. 10 of 2021 and No. 45 of 2022.
The legislative objective of withholding at source is threefold:
Under Section 86 of the Act, any person required to withhold tax becomes a statutory withholding agent. If the withholding agent fails to deduct tax, both the payer and payee become jointly and severally liable to pay the unwithheld tax amount to the Commissioner General of Inland Revenue.
2. The Key Distinction: Withholding Tax (WHT) vs Advance Income Tax (AIT)
A frequent point of confusion for accountants is the terminology difference between WHT and AIT in official IRD gazettes:
3. Current Sri Lanka WHT Rate Schedule & Thresholds
Withholding rates depend strictly on the payment classification, residency status of the recipient, and applicable monthly statutory threshold exemptions.
The primary resident and non-resident withholding categories include:
The LKR 100,000 threshold applies to the aggregate payments made to the same payee within a single calendar month, regardless of whether payments are broken into multiple invoices or split across separate payment vouchers.
4. WHT on Service Fees & Professional Consultancy
Under Section 85(1)(a) of the Inland Revenue Act, any person carrying on a business who pays service fees to a resident service provider must deduct 5% withholding tax if aggregate monthly payments exceed LKR 100,000.
Statutory categories of specified services include:
Key Practical Distinction:
WHT applies exclusively to the service fee component (excluding VAT and SSCL). For example, if an agency issues an invoice for LKR 200,000 + 18% VAT (LKR 36,000) = Total LKR 236,000, the 5% WHT deduction is calculated on LKR 200,000 (LKR 10,000), not on the gross amount including VAT.
5. Withholding Tax on Commercial & Residential Rent
When a business leases commercial property (office space, warehouse, factory, retail outlet) or residential premises for company personnel from a resident individual or corporate entity, rent payments exceeding LKR 100,000 per calendar month attract a 10% Withholding Tax.
Illustrative Rent Calculation:
1. Agreed Monthly Rental: LKR 350,000
2. Statutory WHT Rate: 10%
3. WHT Deducted at Source: LKR 35,000 (remitted directly to the IRD)
4. Net Cash Remittance to Landlord: LKR 315,000
5. Statutory Requirement: Issue WHT Deduction Certificate (Form WHT 01) to landlord within 30 days of calendar month end.
6. Withholding on Interest, Royalties & Dividends
Corporate entities paying interest or distributing dividends must account for specific withholding mandates:
7. Statutory WHT Deduction Certificates & Mandatory Details
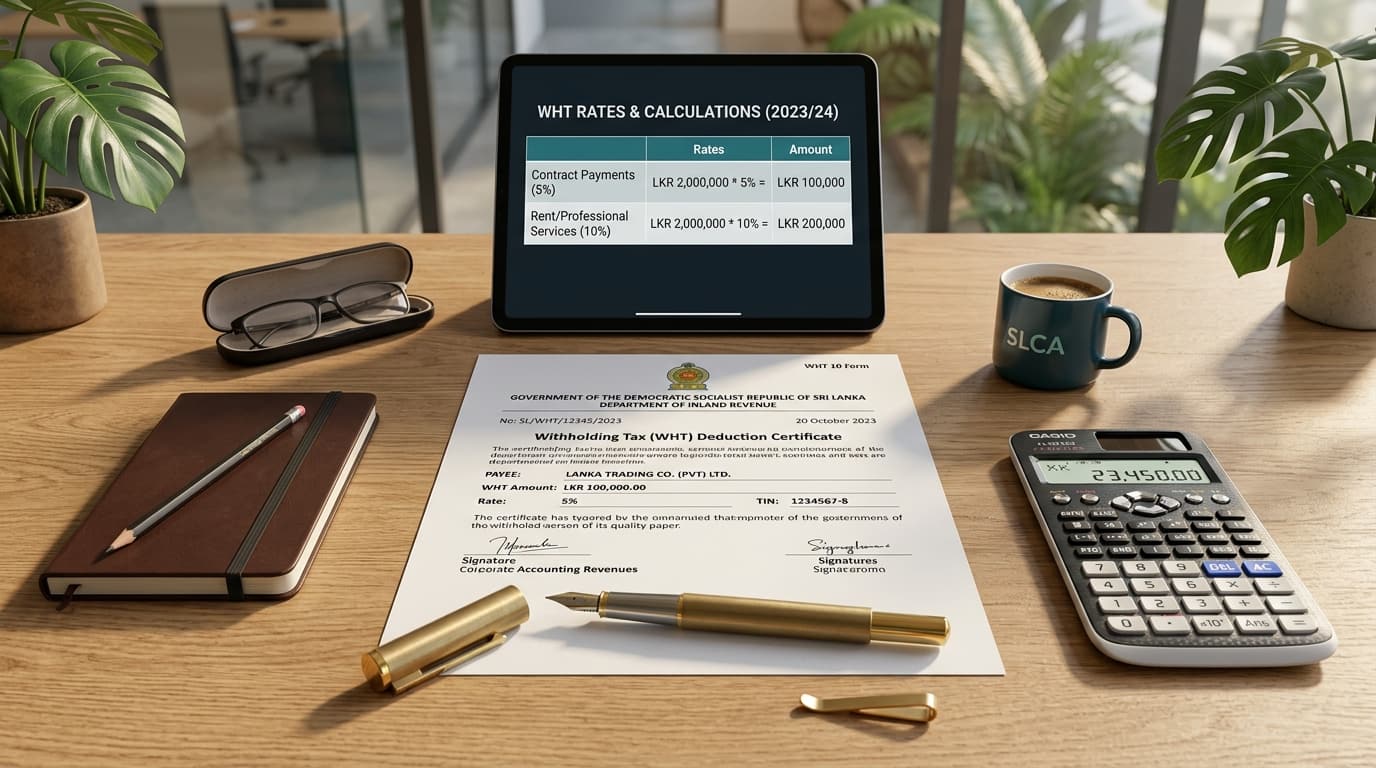
Section 87 of the Inland Revenue Act mandates that every withholding agent must deliver a formal Withholding Tax Certificate to the payee.
A compliant Certificate of Deduction must contain the following statutory fields:
A payee cannot claim credit for withheld tax in their annual IRD RAMIS corporate income tax return without holding the physical or cryptographically verifiable digital WHT certificate issued by the payer.
8. Accounting for WHT: Debits, Credits & Ledger Treatment
In strict double-entry accounting, Withholding Tax must be recognized simultaneously with the supplier bill or rental accrual.
Case 1: Payer Deducting WHT on Vendor Bill (Specified Service Fee LKR 200,000 + 18% VAT):
When the business remits the WHT to the IRD bank account:
Case 2: Payee (Recipient) Subject to WHT Deductions on Customer Invoices:
When a customer pays an invoice net of 5% WHT:
9. Remittance Deadlines & RAMIS Annual Schedule Uploads
Withholding tax compliance requires strict adherence to statutory payment calendars:
10. How SyncBooks Automates WHT Calculations & Certificates
Managing hundreds of vendor payments across varying tax categories manually in spreadsheets creates significant compliance risk. SyncBooks automates withholding tax natively within the core purchasing and banking workflows:
Explore SyncBooks's Tax module to configure vendor WHT rules, auto-generate deduction certificates, and maintain an audit-ready tax register.
11. Frequently Asked Questions (FAQ)
Is Withholding Tax (WHT) still mandatory in Sri Lanka?
Yes. Advance Income Tax (AIT) / Withholding Tax is mandatory under the Inland Revenue Act No. 24 of 2017 (as amended) for specified service fees (> LKR 100k/mo), commercial rent (> LKR 100k/mo), dividends (15%), interest (5%), and non-resident payments.
Does WHT apply to the total invoice amount including VAT and SSCL?
No. Withholding tax is strictly calculated on the base taxable value of the goods or services, excluding VAT (18%) and SSCL (2.5%).
What happens if a company fails to deduct WHT from a supplier bill?
The company becomes legally liable to pay the unwithheld tax amount, plus a 20% statutory penalty and 1.5% monthly compounding interest. Furthermore, under Section 18, the IRD may disallow the entire supplier expense from corporate income tax deductions.
What is the deadline for issuing WHT certificates to vendors?
Withholding agents must issue certificates to payees within 30 days from the end of each calendar month or tax period in which the deduction was made.
Can a business offset WHT Recoverable against its final Corporate Income Tax liability?
Yes. WHT deducted by customers is an advance tax asset on your Balance Sheet and is credited directly against your annual Corporate Income Tax (CIT) liability in your RAMIS tax return.
📌Key Takeaway & Summary
Withholding Tax (WHT) and Advance Income Tax (AIT) compliance in Sri Lanka requires precision, strict threshold tracking, and timely certificate issuance. By leveraging SyncBooks's automated tax engine, finance teams eliminate withholding errors, maintain balanced ledgers, and export pre-validated RAMIS schedules with complete confidence.
Published by the SyncBooks Knowledge & Research Team — Sri Lanka Accounting Cloud.